

I heard from a YouTube video recently that 1 out of 7 calories in the world consumed is in the form of rice. That seemed kind of surprising but correct, and then I looked this statistic up and it seems to actually be in the range of 1 out of 5 calories in the world comes from rice. It’s a wonderful food source, highly concentrated and dense in calories when its dry and easily stored in sacks. It’s a commoditized product, you can buy a large 50lb bag of jasmine rice and get 300-400 servings out of it depending on how much rice you use per serving. Comes down to around 10-20 cents per serving, it’s not hard to image how this food source keeps people fed.
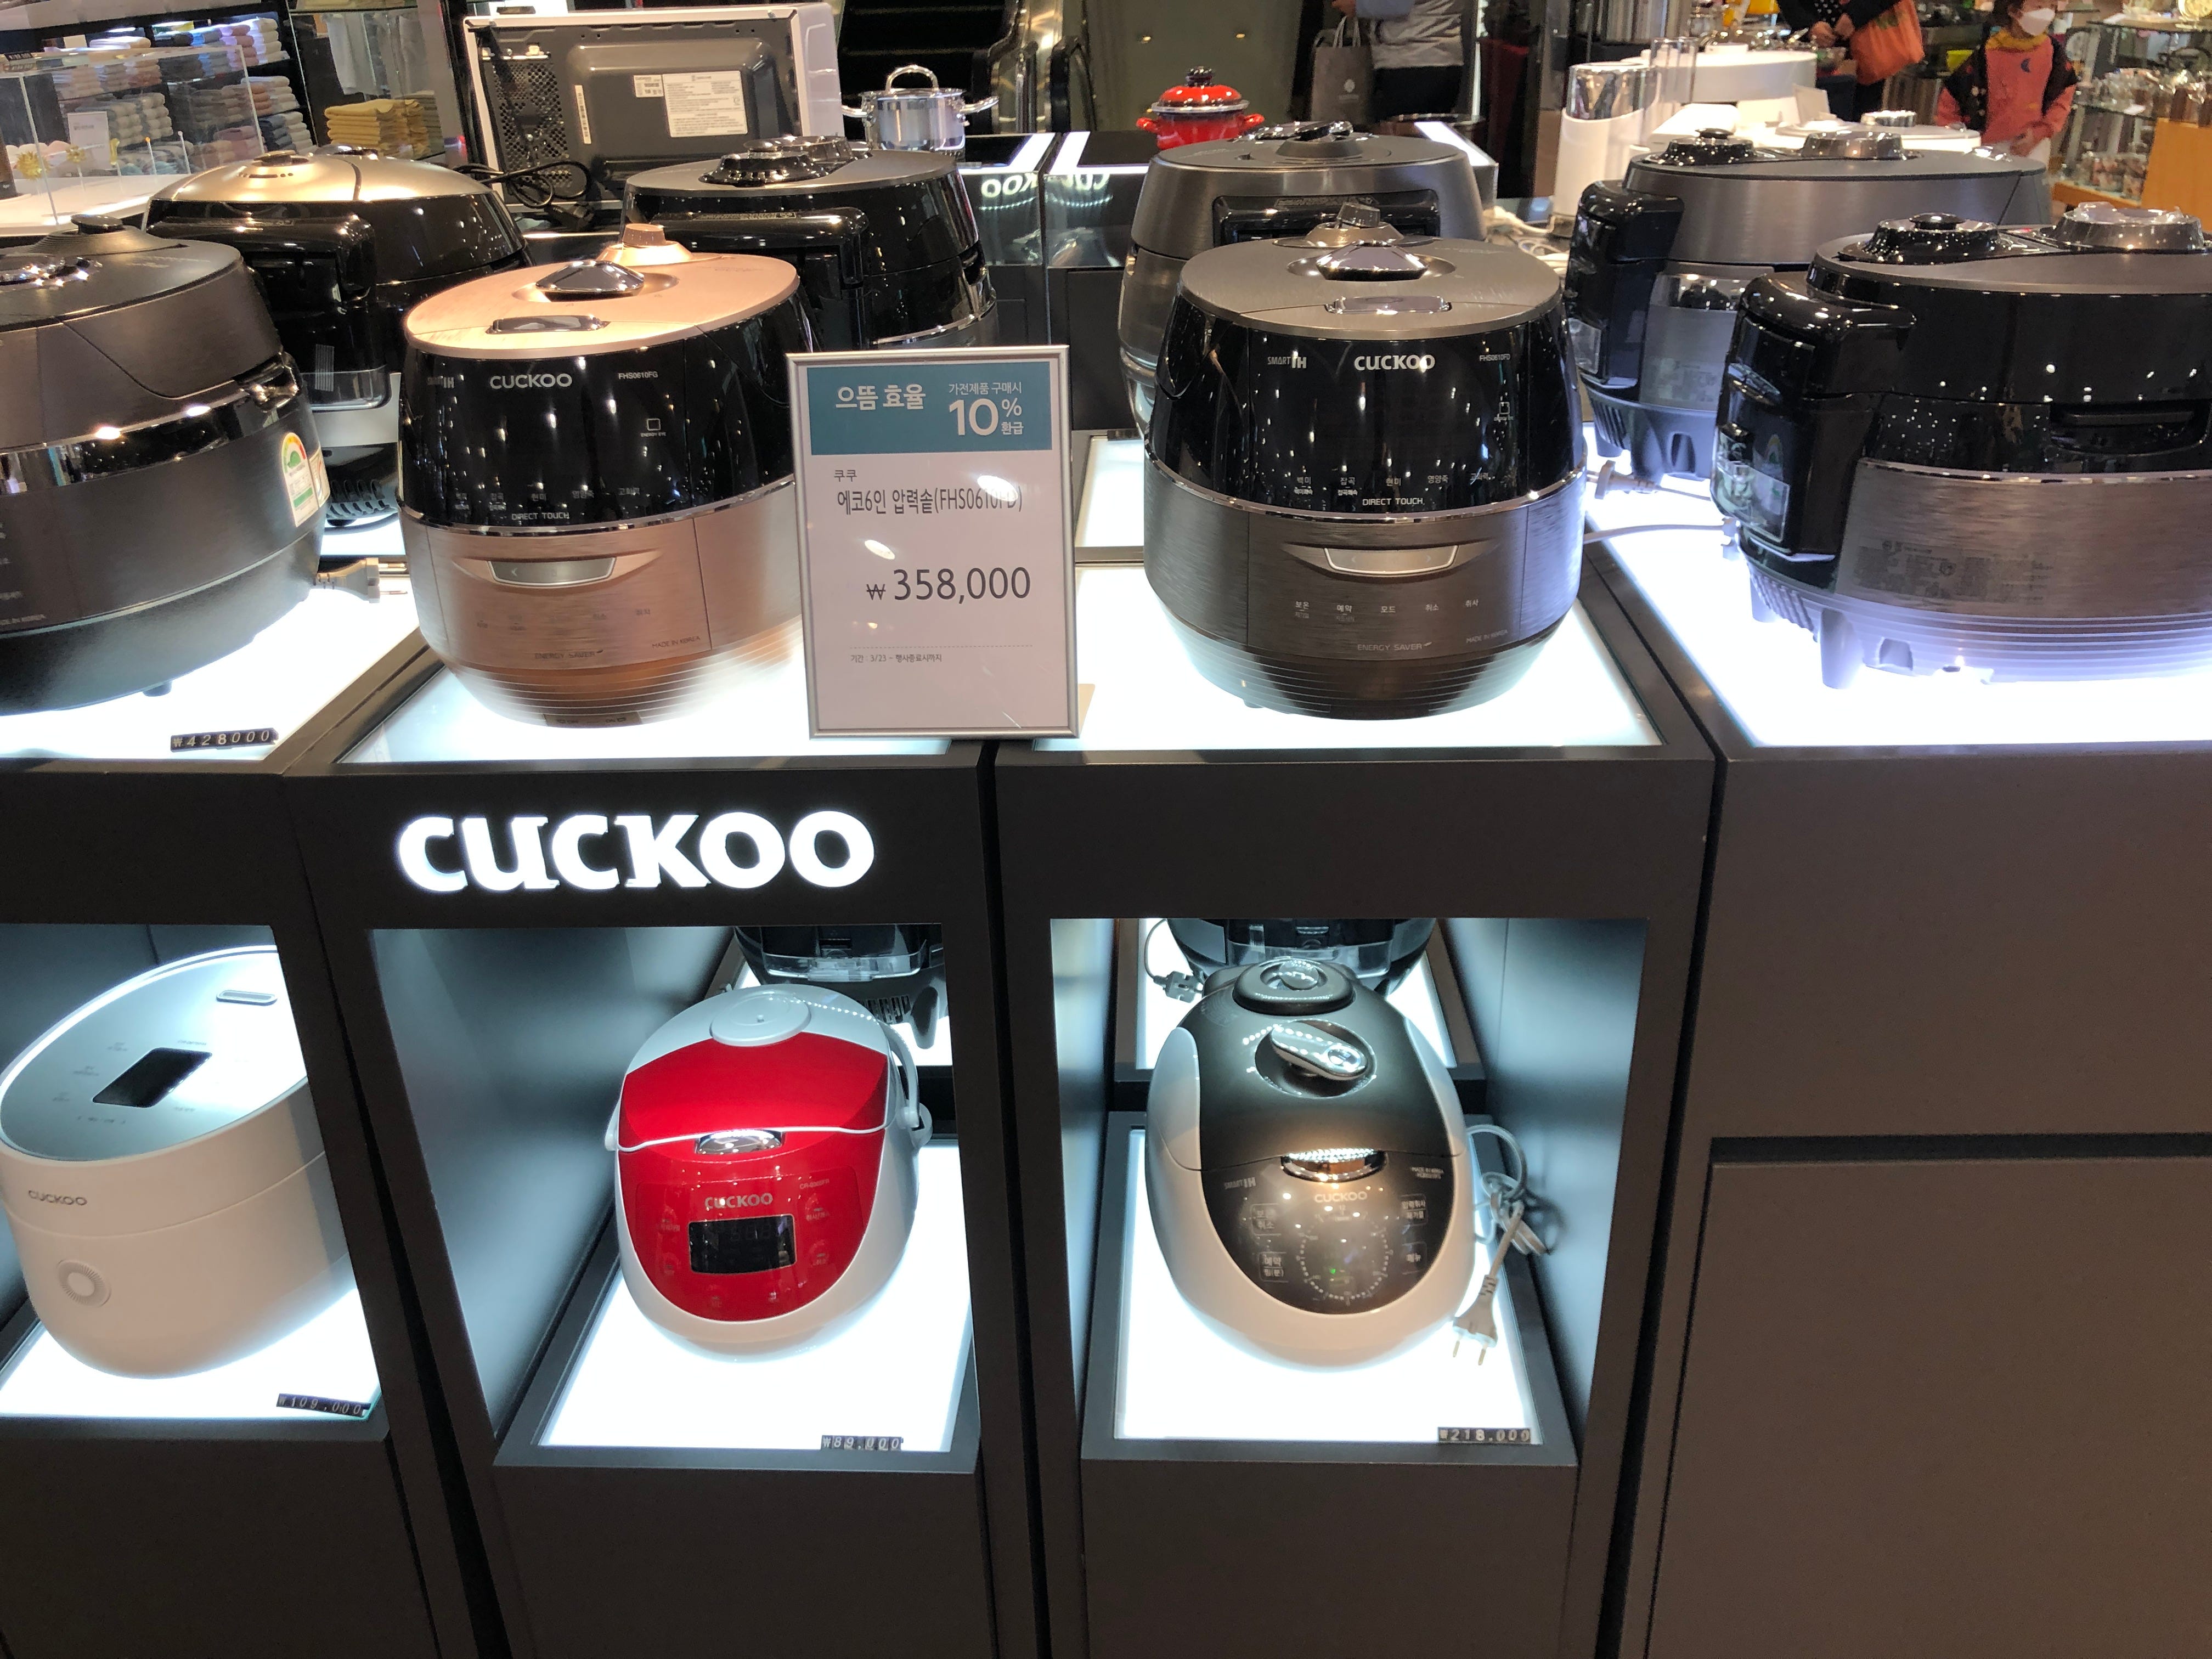
However, I’m not looking at investing in rice paddys today, but rather in rice cookers. In my last post I was talking about the Korea trade and one of the names I mentioned was Cuckoo Holdings. It wouldn’t be hard to find something like Cuckoo Holdings just flipping through screens or going A-Z until you find some good names on asset basis, earnings or both. You may be familiar with their product, they may be the #2 or #3 well known rice cooker brand behind Zojirushi, Tiger or Toshiba and an affordable one at that:
Business Figures and Ratios
Price: ₩27,400 (As of 8/18/2026)*
*Note: Some prices utilized in parts of this writeup/calcuations may vary a bit as I worked on it on and off the last 2 weeks, should be minimal difference in regards to the thesis
Market Cap: ₩851b
P/E - Owners Earnings: 5.7x
EV/EBIT: 4x
P/TBV - Liquidation Value: 0.65x-0.75x
Dividend Yield: 5.9% @ 25% Payout Ratio
Z-Score: 5
ROE - ex-Cash Normalized: 12.5%
Background & Business
Cuckoo Holdings is a Korean holding company that is engaged primarily in the manufacturing, R&D and sale of rice cookers and secondarily in sale or lease of kitchen and lifestyle appliances.
They were founded in 1978 as Sungkwang Electronics by Ja-Shin Koo producing basic electronic components and small appliances. In 1955 a Toshiba inventor created the first modern rice cooker which fueled Japan’s economic miracle years and a race to capture the market ensured with other makers such as Zojirushi and Tiger among many others. Sungkwang entered the market with an LG partnership in 1982 to develop a model specialized for the Korean tastes which became Cuckoo in 1998. Like many great business stories, the Cuckoo rice cooker was so successful that they changed the name of the entire company to Cuckoo Co., Ltd. in 1999.
The business in later years diversified a bit into water purifiers, home appliances and appliance rental/leasing business. They went public in 2014 at ₩104,000/sh and then restructured into a holding company primarily operating the Cuckoo Electronics, Homesys and a few other minor distributing/operating subsidiaries ever since.
Cuckoo today is a dominate brand in South Korea and I think calling it a duopoly with along with Cuchen does it a disservice. Cuckoo holds a 70%+ market share in the rice cooker category in Korea. It is extremely entrenched into the daily lives of the Korean household. A rice cooker frequently is a wedding gift or gift to Koreans abroad:
Translated from the link: https://finance.ettoday.net/news/1248277
For many Koreans, this electric pot is even their connection to their hometown Bobby Yoon, a Korean man who opened a restaurant in New York, said that when he was studying in Pennsylvania, his mother in South Korea sent him a Cuckoo to the dormitory, but it was unusable because of the different plugs. Yoon said, “My mother knew I I cried when I couldn’t use it, and the electric cooker weighed so much on Korean families
I’ve looked around and asked AI for other brands that have this level of market concentration and it’s difficult to come up with some good comparisons.
Operating Companies, Revenue Breakout & Outlook
The holding company has two major operating companies that drives about all of the revenue for the holdco.
Cuckoo Electronics (100% Stake) - Manufacturing and sale of rice cookers, induction ranges, microwaves and dishwashers. Most of the revenue will be from rice cookers while mature still slowly growing while the non-rice cooker appliances have been their new growth engine.
Cuckoo Homesys - 284740 KR (40.55% Stake) - Rental and sale of kitchen and lifestyle appliances such as Water Purifiers, air purifiers, bidets and vacuum cleaners. A decent growing business at 7%-8% revenue growth per year.
For financial statement reporting purposes the revenue line is 100% from Cuckoo Electronics, however they do stuff the 40.55% of revenue from Cuckoo Homesys as some sort of equity investment income/(loss) kind of line item. Just combining the 100% from Cuckoo + 40.55% of Homesys revenue the holding company generates 67% from Cuckoo Electronics and 33% from Cuckoo Homesys.
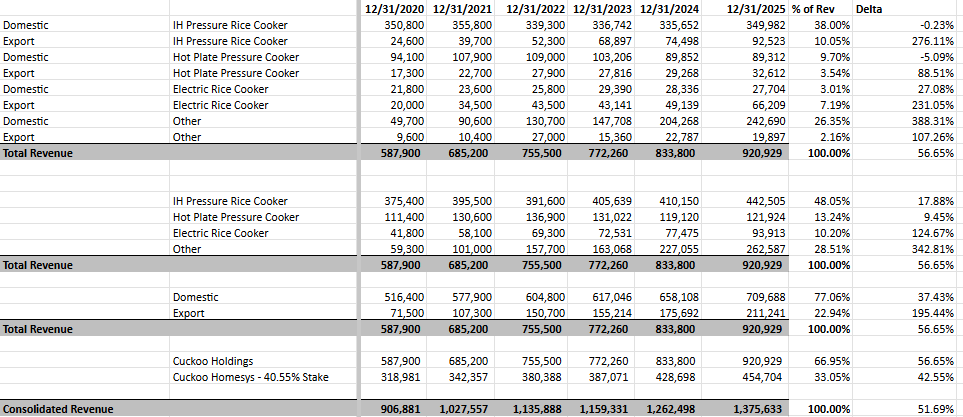
Outside of all of this, both sides of the domestic and export market have been doing well. The export market has been a great source of revenue growth for the business I imagine and there’s probably considerable upside for them to continue to grow this part of the business especially with the currency advantages with the Won vs USD or EUR for example.
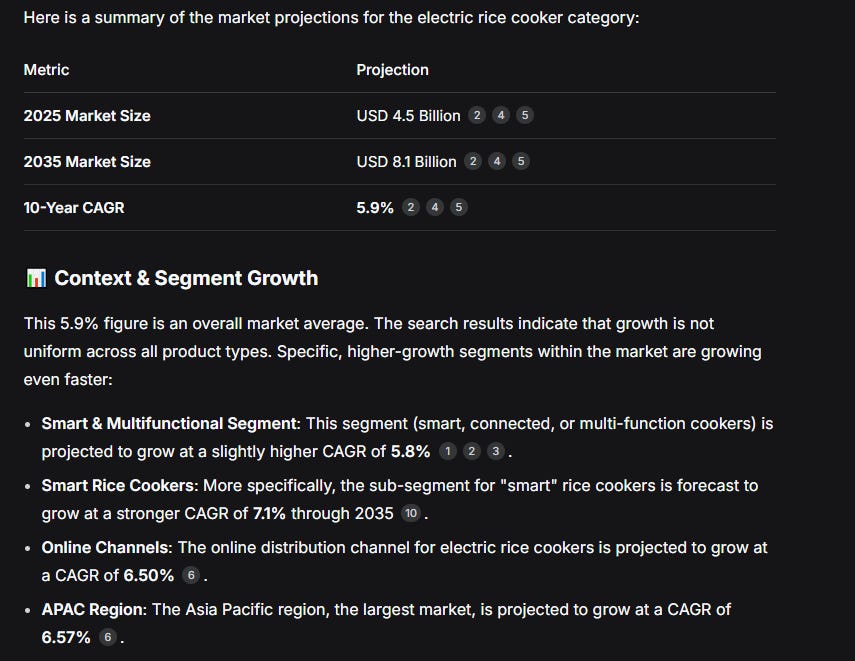
The outlook for rice cookers is around the rate of inflation if not a bit more. Asking around AI references various research reports puts it around 5-7% CAGR in the next 10 years. This depends on the rice cooker segment with smart and IH technology being higher growth and the basic traditional technology maturing. There’s still a lot of growth in the export market outside of the maturing Chinese market which seems about right when I look at how the export business has performed at Cuckoo.
There’s been a general trend with kitchen appliances globally in the recent decades that has slowly isolated functions that you normally perform on a stove into its own product. This may be for energy efficiency sake, convenience sake or what you have to do with smaller kitchens.
More smaller batch cooking and baking is done in air fryers, instead of cooking rice and other grains in a pot on the stove you cook it in a rice cooker, instead of cooking in a dutch oven you may cook meat in a crockpot. You also have appliances like the instapot that tries to be an all in one which can cannibalize all categories.
Main Catalyst - Value-Up Disclosure
The company disclosed a value-up this year and states the following (translated from KR to EN):
Goal Setting: In order to improve corporate value, our company sets growth potential, profitability, and shareholder return as key indicators, and aims to continuously increase shareholder value by expanding shareholder returns such as dividends based on stable growth in the mid to long term. In addition, we aim to build a virtuous cycle of growth and shareholder returns based on strengthening business competitiveness and securing financial soundness.
Planning: Our company plans to strengthen product competitiveness and advance our business portfolio in various areas of home appliances, including kitchen appliances. To this end, we will continue to promote R&D investment and strengthening product competitiveness based on differentiated technology and quality competitiveness, and strengthen our growth base by expanding our product lineup and targeting overseas markets, focusing on major dependent companies. In particular, we plan to improve profitability and cash generation by expanding premium products and improving product mix. In addition, we will promote the sustainability and gradual expansion of dividends based on stable cash generation, and strengthen shareholder returns through various shareholder return policies such as the use of treasury stocks. Through this, our company will build a virtuous cycle of growth and increased shareholder value.
Most of this is will read like standardized text for how companies announce these value-up programs, however this company has already been doing some of what they have described. Dividends have increased from ₩659/sh in 2021 to ₩1,550/sh so far in 2026. That represents a 26% annual growth rate in the dividend. To add in further, if there is some set payout ratio maybe 20%-25% of earnings, the dividend will grow as the earnings grow year over year.
As for the R&D spend, it is true they have been increasing the R&D spend, still hovers around 1% of sales (not including Homesys). It’s not really clear how much of this will to maintain the business as it is, rice cooker technology doesn’t particularly change all that much, my guess is they may increase these investments to grow their non-core/mature part of the business with household/lifestyle appliances.
Appraisal Value
I’ll pull out a Buffettism or Grahamism where there was a quote along the lines of “You don’t need to know a man’s weight to know that he’s fat.” You can eye ball some multiples or simple calculations and see that the stock is ridiculously cheap on an asset or owners earnings basis. My back of the envelop math below:
Asset Value
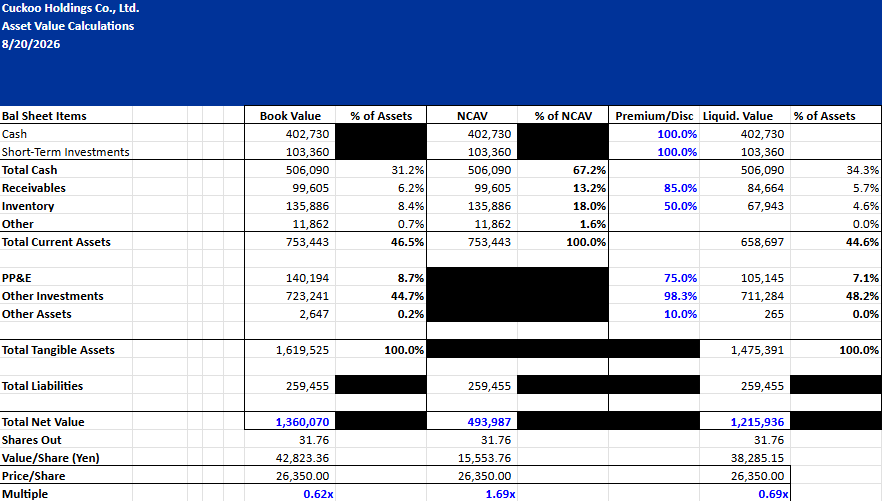
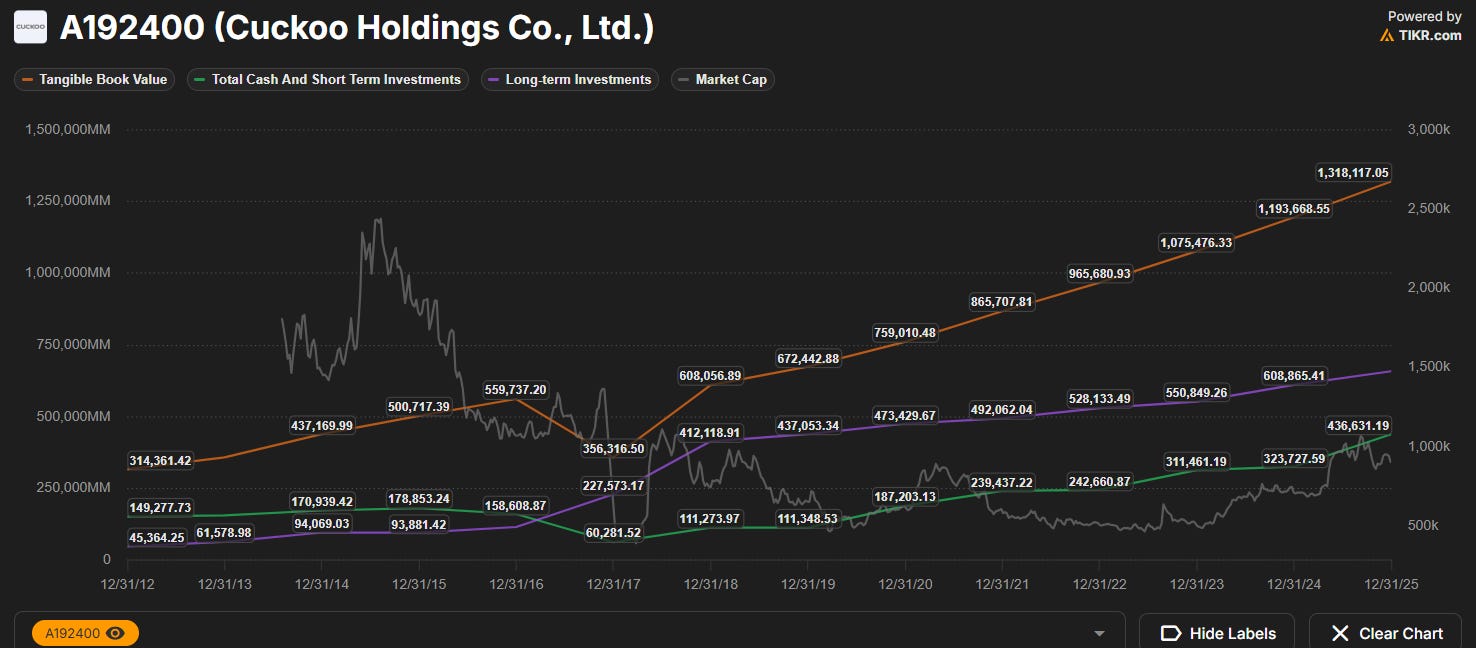
Most of this exercise is pretty straight forward, most of the assets will be in cash or in other investments, so I’ll focus there. Cash consists of cash, deposits and other short-term investments so we can take values as is on the balance sheet.
The other major piece is the other investments and that consists of investment real estate at ₩80b and equity investments at ₩642b. I don’t really have any solid info on where to start on the investment real estate and its around 6% of tangible assets so we can pass.
As for the equity investments. About ₩335b is in Homesys in historical cost vs their market value of ₩202b (₩497b * 40.55%), so a -40% decline from their investment. However, Homesys trades at a P/E of 4x for a business that has over 10% ROCE, sounds ridiculous but I don’t think it’s insane to say in a full liquidation they can get double today’s stock price for that operating entity. So in the end I think other investment may be worth around ₩711b in liquidation value (₩642b total equity investments - ₩335b of Homesys book cost + ₩404b fair market value of Homesys in a hypothetical sale). The rest of the equity investments involve private equity stakes in subsidiaries for product distribution channels in other countries.
So in the end we get ₩38,285/sh of liquidation value at 0.69x today’s share price which is a pretty rough estimate but I’m comfortable with.
What’s the business worth on an asset basis? If the enterprise is capable of generating over 10% after-tax ROE or ROCE, normalized for excess cash, it should trade for at least book value, so around 38,285/sh (45% from today’s price). Zojirushi (7965 JP) trades around 1x book and I don’t think that business is much better than Cuckoo.
Owners Earnings
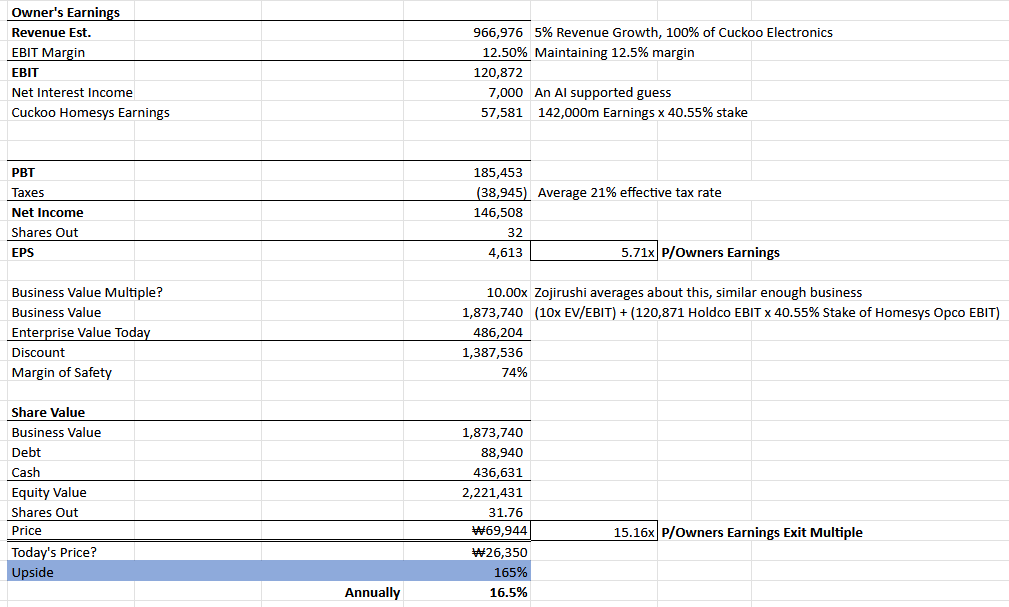
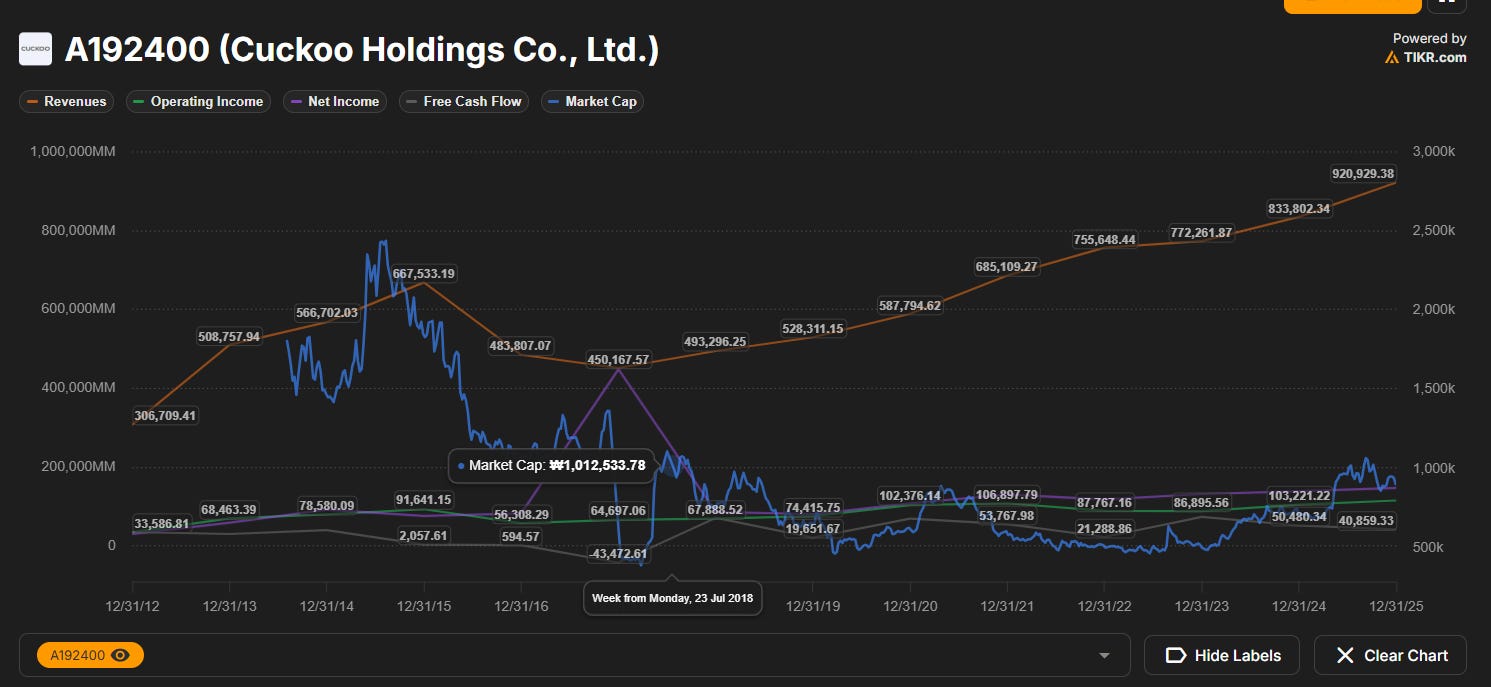
The path to the company generating ₩4.6b in owners earnings is very achievable with some of the conservative assumptions in place. Keep in mind Cuckoo Homesys Earnings don’t appear at the revenue line and get pushed in down the income statement. I took a simple approach and added in 40.55% of their most recent earnings.
I believe Cuckoo Holdings is worth 10x EV/EBIT (165% from today’s price), similar to Zojirushi (7965 JP) in Japan that trades on average around 8x-10x while generating what may be around 6%-8% ROE. With Cuckoo at 12.5% ROE I think we can justify a 10x EV/EBIT multiple, which at ₩69,944/sh would have it at 15x our price to appraisal value, Zojirushi trades at LTM P/E of 15x today.
Potential Upside
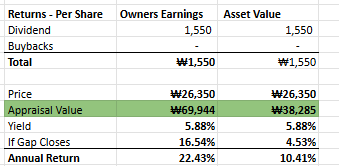
Combining the two methods, we have a scenario that has a lot of potential in generating decent returns with a significant margin of safety. This also underestimates the fact that there will be continuously dividend increases. If re-rating happens in less than 10 years the returns would be quite strong at these price levels.
Should We Buy Cuckoo Homesys?, Tax Inheritance Planning?
One of the questions that I had in my mind is that should we instead buy Cuckoo Homesys (284740 KR), the sole publicly traded operating company? It’s incredibly cheap just looking at the initial view of the numbers. 4x LTM P/E, 0.45x P/BV, growing high single digits, above average returns on equity, and so on. Assuming there’s similar financial alignment with insiders Homesys as there is with Holdings, perhaps we can:
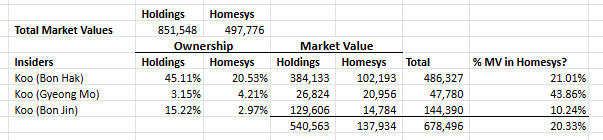
Insiders own more of the Holdco, however they are invested enough into Homesys in my opinion that I doubt they would want to do any shareholder unfriendly actions with the operating company that would hurt the long-term performance of the stock given the tax inheritance planning from the founder to his heirs have concluded in 2021. However it’s not clear to me if incentives work the same in Korea. Many of the family control situations don’t seem to care that much about their stock performance vs keeping control of the family business.
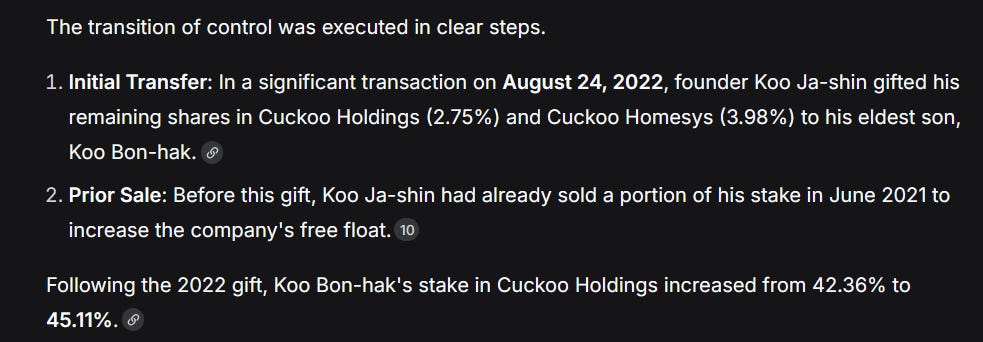
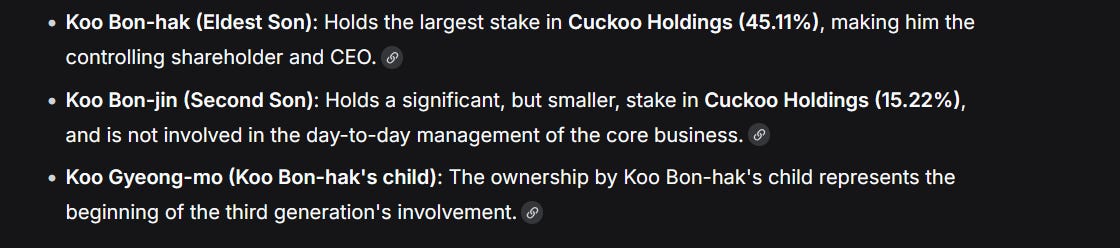
The only other piece that somewhat bothers me with this situation as well as many others in Korea is that if Homesys is an above average business or even someday a great business depending on how that segment works out, why even let the public have 59.45% or whatever ownership in this thing? Why not own the whole thing?
Coming from the more greedy western markets if you have a business with a small stake in a related operating company that is doing well trading at depressed multiples investors will ask why is the public allowed to own the rest of a good running business instead of the holding company. Why are we not increasing our economic interests in that business? I don’t have answers but stocks don’t get this cheap without there being some wear and tear on the thesis.
Conclusion
Cuckoo Holdings is a great entry point into the South Korea trade. The holding company structure is easier to understand than most, avoids the general tax inheritance/family succession issues and its a simple easy to understand business and idea. It seems like there’s so many ideas that are similar to this where you aren’t really competing on uncovering information, you’re competing on just entering the market and buying a position, many don’t but overtime that may change as the Korean market reforms play into effect.
There is nothing really interesting, hidden or eye popping about this stock, it’s a beloved blue chip rice cooker brand where you can purchase ₩4,600/sh of owners earnings or ₩38,285/sh of adjusted net tangible assets for ₩27,400/sh, collect the 6% dividend yield and wait for the value-up catalyst to workout or for investors to notice. It’s an average to above average business trading at Graham & Dodd prices and holding a basket of those type of ideas tend to do very well.
Risks
South Korea Corporate Governance Issues: While the tax inheritance planning issue is behind us, there can still be potential for abuse for minority shareholders which has been common in Korea but improving overtime.
Value-Up Initiative Underperforms: If the Value-Up initiatives doesn’t work out and ends up being just a performative filing, this could hurt investor confidence in the Korea market to realize value.
Losing Market Share: While Cuckoo is a phenomenal brand in South Korea, a 70%+ market share also means a big pool for competitors to constantly test the resilience of and any cracks in that competitive advantage could cause business deterioration.
Foreign Currency Risks: Cuckoo has a big export market that is quickly growing, results could get really volatile around earning in foreign currencies and returning it back in KRW.
Disclosure: I own a long position 192400 KR, no position in 284740 KR - I may purchase shares in the future. I am not short on any positions mentioned in this post. I may add or sell my long positions over time. I only manage my own personal accounts and do not manage outside capital. Nothing here is a recommendation to buy or sell securities, nothing here is financial or tax advice, please DYODD.
8/24/2026 Update - Additional Reading:
Wanted to thank Asian Century Stocks for highlighting this write-up this morning on his weekly asia posts:
https://www.asiancenturystocks.com/this-week-in-asia-40/
From this Michael highlighted a VIC post that I wasn't aware of that does really get into the weeds of a lot of the tangible issues and holdings/subs details worth reading about.
https://valueinvestorsclub.com/idea/Cuckoo_Holdings/7121463605?ref=asiancenturystocks.com#description
Sell Side Report from Comments section of VIC write-up:
https://download.nhqv.com/CommFile/cis/rsh/epr/CISPPR20241022161827712.pdf
A few updated thoughts from that VIC post below:
1. It's clear why the structure was introduced. In that Homesys originally was a larger shareholder of Cuckoo Electronics with the eldest son having a large stake. So the structure ended up normalizing the shareholding between the two entities and avoided messing up the financials if homesys got consolidated.
I'm not sure I 100% agree but if family members are on both sides of the entities with shares tied up, perhaps the idea is that you can think of all of Cuckoo as a single investment from the individuals perspective instead of through the holdco where they would be forced to consolidate. The author makes the case that this is more transparent, I tend to agree but time will tell.
2. I agree with the author that this is a clearer/simpler holdco stucture to invest in within Korea. The alignment with common shareholders seems more realistic/feasible vs some others that have multiple layers and rarely ever wholely owning an operating business. At least here Cuckoo Holdings own the crown jewel in the rice cooker business.
3. The author's points on how fast Cuckoo has gotten brand dominance and it's piece on the Malaysian IPO (CKI) for the Homesys Opco is worth reading. There's just multiple boxes that get checked on this being a higher quality business then the numbers suggest.
Disclosure: No position on CKI MY or 284740 KR, I may consider buying shares in the future.